An accounting ledger is an organized record of a business’s financial transactions. It provides a central place to record account activity, including debits, credits, and balances, and serves as an important foundation for financial reporting and analysis.
Every business needs an accurate way to track its financial activity. While accounting software can automate much of the process, understanding how a ledger works remains important for maintaining organized records and reviewing financial information.
A well-maintained accounting ledger can help businesses monitor individual accounts, reconcile transactions, identify errors, and prepare financial statements. In this guide, you will learn what an accounting ledger is, how it works, what information it contains, and how to use an accounting ledger template effectively.
What Is an Accounting Ledger?
An accounting ledger is a detailed record of financial transactions organized by account. It collects transactions that affect a particular account and shows how those transactions change the account balance over time.
Ledger accounts may be used to track assets, liabilities, equity, revenue, expenses, and other accounts included in an organization’s accounting system.
For example, a business may maintain separate ledger accounts for cash, accounts receivable, sales revenue, office supplies, rent expense, accounts payable, and other financial categories.
Each transaction is recorded with relevant information such as the date, reference number, description, debit, credit, and resulting balance.
Why Is an Accounting Ledger Important?
An accounting ledger helps organize financial information so that transactions can be reviewed and summarized efficiently. It provides a structured record that supports bookkeeping and financial reporting.
- Organizes financial transactions: Transactions are grouped according to their associated accounts.
- Tracks account balances: Businesses can monitor changes in individual accounts over time.
- Supports financial reporting: Ledger information contributes to reports such as the income statement and balance sheet.
- Helps identify errors: Reviewing individual transactions can make unusual or incorrect entries easier to find.
- Supports reconciliation: Ledger records can be compared with bank records, invoices, receipts, and other documentation.
- Improves financial visibility: Organized account information makes it easier to understand business activity.
- Creates an audit trail: Properly documented transactions provide a record of how account balances changed.
What Does an Accounting Ledger Include?
The structure of an accounting ledger can vary depending on the accounting system and the type of account being tracked. However, a basic ledger commonly contains several important fields.
Account Name
The account name identifies the account being tracked. Examples include Cash, Accounts Receivable, Sales Revenue, Office Supplies, and Rent Expense.
Account Number
Many accounting systems assign an account number or code to each ledger account. A consistent numbering system can make accounts easier to organize and reference.
Date
The transaction date identifies when the financial activity occurred or was recorded according to the organization’s accounting procedures.
Reference Number
A reference number can connect a ledger entry to a related invoice, receipt, journal entry, purchase order, payment, or other accounting document.
Description
The description briefly explains the transaction. A useful description provides enough information to understand why the entry was recorded.
Debit and Credit
Debit and credit columns record the accounting effect of a transaction. The treatment of a debit or credit depends on the type of account and the accounting system being used.
Balance
The balance shows the resulting amount in the account after the transaction is recorded. Maintaining an accurate running balance can make account review easier.
Types of Accounting Ledgers
Businesses may use different types of ledgers depending on the level of detail and the accounting information they need to organize.
General Ledger
The general ledger is the central collection of accounts used to organize a business’s financial transactions. It provides the account-level information used to prepare financial reports.
Subsidiary Ledger
A subsidiary ledger provides more detailed information for a particular category of accounts. For example, an accounts receivable subsidiary ledger may contain individual customer balances that support the corresponding general ledger account.
Accounts Receivable Ledger
An accounts receivable ledger tracks amounts owed by customers. It can help businesses monitor invoices, payments, credits, and outstanding customer balances.
Accounts Payable Ledger
An accounts payable ledger tracks amounts a business owes to vendors or suppliers. It can help organize bills, payments, and outstanding obligations.
Accounting Ledger and Double-Entry Bookkeeping
In double-entry bookkeeping, each financial transaction affects at least two accounts. The corresponding debit and credit entries are recorded so that the accounting records remain balanced according to the accounting framework being used.
The journal and ledger have different roles. A journal generally records transactions in chronological order, while the ledger organizes those transactions by account.
For example, when a business purchases office supplies for cash, the transaction may affect both an office supplies account and a cash account. The entries are ultimately reflected in the appropriate ledger accounts.
Accounting Ledger vs. General Ledger
The terms accounting ledger and general ledger are closely related, but they are not always used in exactly the same way.
An accounting ledger can refer broadly to a record used to track transactions for an account. A general ledger specifically refers to the central set of accounts that summarizes an organization’s financial activity.
In everyday business use, people may use the terms interchangeably when discussing basic ledger records. The exact terminology depends on the accounting system and context.
How to Create an Accounting Ledger
1. Identify the Account
Start by determining which account the ledger will track. Clearly record the account name and, if applicable, its account number.
2. Determine the Reporting Period
Define the period covered by the ledger. This might be a month, quarter, year, or another period that fits the organization’s accounting process.
3. Gather Supporting Records
Collect relevant invoices, receipts, payment records, journal entries, bank information, and other supporting documents needed to accurately record transactions.
4. Record Transactions
Enter each transaction using a consistent format. Include the date, reference number, description, debit, credit, and balance where appropriate.
5. Verify the Entries
Review each entry for accuracy. Compare transaction amounts with the supporting documentation and check that the entries have been assigned to the appropriate accounts.
6. Calculate the Running Balance
Update the account balance after each transaction. A running balance provides a convenient view of how the account changes throughout the period.
7. Reconcile the Records
Where appropriate, compare ledger information with external records such as bank statements, customer accounts, vendor records, or other supporting documentation.
How to Use an Accounting Ledger
An accounting ledger becomes more useful when it is maintained consistently. Businesses should establish a routine for recording transactions and reviewing account activity.
- Record transactions promptly.
- Use consistent descriptions and reference numbers.
- Keep supporting documentation organized.
- Review unusual transactions or unexpected balances.
- Reconcile relevant accounts regularly.
- Correct errors using appropriate accounting procedures.
- Maintain records according to applicable business and accounting requirements.
The exact procedures for correcting entries, retaining records, and preparing financial statements can depend on the accounting framework, business structure, jurisdiction, and professional accounting practices involved.
Accounting Ledger for Small Businesses
A small business can use an accounting ledger to organize transactions even when its accounting process is relatively simple. A basic ledger can provide a structured view of income, expenses, assets, liabilities, and other accounts.
For a small business, a ledger may be maintained in accounting software, a spreadsheet, or a printable accounting ledger worksheet. The right method depends on transaction volume, reporting needs, internal controls, and the complexity of the business.
As transaction volume increases, accounting software can provide features such as automated posting, reconciliation, reporting, and transaction categorization that may be difficult to manage manually.
Tips for Maintaining an Accurate Accounting Ledger
- Record transactions consistently: Use the same structure and terminology throughout the ledger.
- Keep source documents: Store invoices, receipts, statements, and other supporting records in an organized system.
- Review entries regularly: Frequent reviews can help identify mistakes sooner.
- Reconcile accounts: Compare ledger balances with appropriate external records.
- Use reference numbers: Linking entries to supporting documents makes transactions easier to trace.
- Protect accounting records: Use appropriate access controls and backups for digital records.
- Avoid unnecessary alterations: Follow established accounting procedures when correcting mistakes.
- Keep the ledger current: Delayed entries can make account balances less useful for decision-making.
Common Accounting Ledger Mistakes to Avoid
Inaccurate ledger records can affect financial reporting and make account reconciliation more difficult. Common mistakes include:
- Entering a transaction in the wrong account
- Recording the wrong transaction date
- Entering incorrect amounts
- Omitting transactions
- Recording the same transaction more than once
- Using inconsistent reference numbers
- Failing to update the running balance
- Ignoring discrepancies during reconciliation
- Losing or failing to organize supporting documentation
A regular review process can help identify these issues before they affect larger financial reports.
Using an Accounting Ledger Template
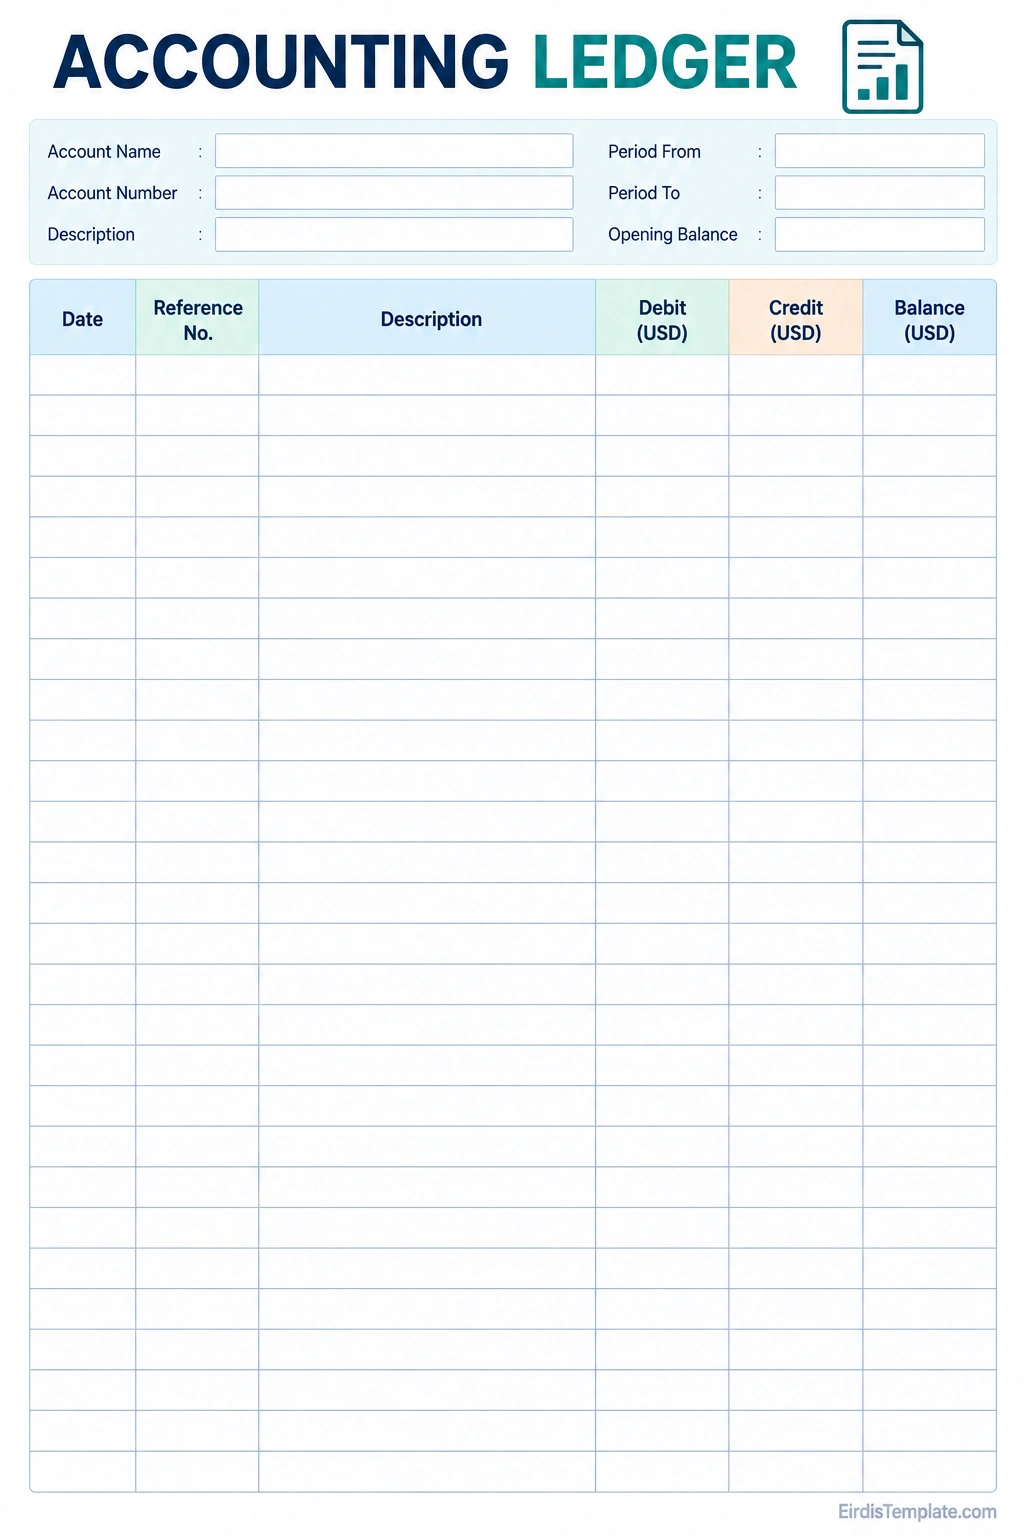
An accounting ledger template provides a structured format for recording financial transactions. A typical template includes fields for the account name, account number, reporting period, transaction date, reference number, description, debit, credit, and balance.
A printable accounting ledger template can be useful for manual bookkeeping, transaction review, classroom accounting exercises, small business recordkeeping, or as a simple supplementary worksheet alongside an accounting system.
Before using a template for actual business records, customize the columns and account structure to match the organization’s accounting process. A basic template should complement, rather than replace, appropriate bookkeeping and accounting procedures.
Frequently Asked Questions About Accounting Ledgers
What is an accounting ledger?
An accounting ledger is an organized record of financial transactions grouped by account. It tracks account activity and balances and provides information used in financial reporting.
What is the purpose of an accounting ledger?
The purpose of an accounting ledger is to organize financial transactions, track account balances, support reconciliation, and provide detailed information for financial reporting and analysis.
What information is recorded in a ledger?
A basic ledger can include the account name, account number, transaction date, reference number, description, debit, credit, and resulting balance.
What is the difference between a journal and a ledger?
A journal generally records transactions in chronological order, while a ledger organizes transactions by account. Information from journals is used to update the appropriate ledger accounts.
What is a general ledger?
A general ledger is the central collection of accounts used to organize a business’s financial transactions and support the preparation of financial reports.
Can a small business use an accounting ledger template?
Yes. A small business can use an accounting ledger template to organize transactions and monitor account activity. The template should be adapted to the business’s accounting process and reporting needs.
Is an accounting ledger still useful with accounting software?
Yes. Accounting software typically maintains ledger information electronically and automates many accounting processes. Understanding the structure of a ledger remains useful for reviewing transactions and understanding financial reports.
How often should an accounting ledger be updated?
The appropriate frequency depends on the business’s transaction volume and accounting process. Recording transactions promptly and reviewing accounts regularly can help keep financial information current and useful.
Conclusion
An accounting ledger is a fundamental tool for organizing and tracking financial transactions. By grouping account activity and maintaining clear records of debits, credits, and balances, a ledger provides important information for bookkeeping, reconciliation, financial reporting, and business analysis.
Whether maintained digitally or with an accounting ledger template, accurate records can make it easier to understand financial activity and prepare reliable reports. A consistent process, regular reconciliation, organized supporting documents, and careful review are key to maintaining useful accounting records.
Download: Accounting Ledger Template

- Printable Acknowledgement Receipt Template - October 1, 2026
- Free Acknowledgement Letter Template (Word) - October 1, 2026
- Free Printable Accounting Ledger Template - October 1, 2026
